
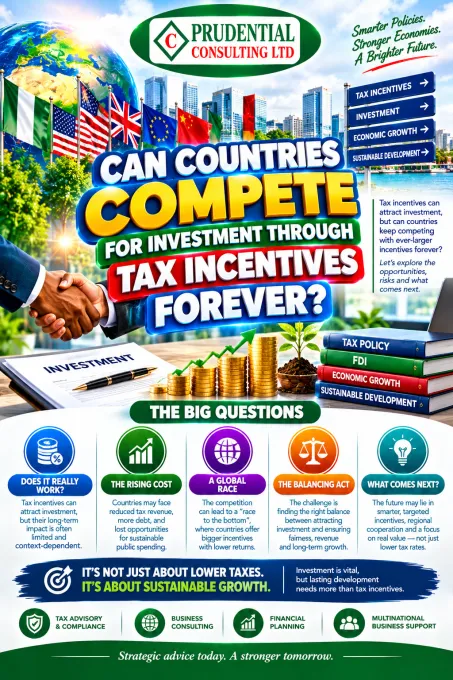
Governments have long used tax holidays, reduced rates, and special allowances to attract investment. The practice raises a fair question for business owners and policymakers: how long can countries keep competing this way? Rules on global minimum tax, pressure on public revenue, and mixed evidence on results all point toward a change in how incentives are designed. Nigeria’s own reforms show this change clearly.
How Tax Incentive Competition Works
When a country offers an incentive, it gives up some tax revenue in the hope of attracting investment that would not otherwise arrive. When neighboring countries respond with their own offers, the benefit to any one country can shrink while the revenue cost to all of them remains. Three pressures now limit this approach:
- Minimum tax rules. Where a group’s effective tax rate in a country falls below 15 percent, a top-up tax may be collected elsewhere, which reduces the value of a pure rate cut for in-scope groups. Commentators have noted that this moves competition away from rate cuts and toward subsidies and tax credits linked to real spending.
- Revenue needs. Governments are placing more weight on domestic revenue and are asking whether incentives deliver value in return.
- Evidence. Research on Nigeria has found that incentives can support investment in the short run, while their longer-term effect depends on institutional quality and macroeconomic stability.
What Nigeria Has Changed
In November 2025, the Nigerian Investment Promotion Commission (NIPC) announced that it would stop accepting new Pioneer Status Incentive applications to allow a transition to the Economic Development Tax Incentive (EDTI), which took effect on 1 January 2026. Published NIPC information describes the EDTI as a 5 percent tax credit on qualifying capital expenditure for eligible companies investing in priority sectors listed in the Tenth Schedule of the Act. The shift is from time-based relief to relief tied to the amount invested.
Reports in September 2026 noted that tax breaks valued at about ₦3.87 trillion were facing scrutiny, with analysts asking whether they had produced enough investment, and calling for incentives that are better targeted, openly administered, and tied to measurable results such as new investment, jobs, exports, and productive capacity.
Step-by-Step: How a Business Should Approach Incentives
- Identify the incentives that apply to your sector. Check whether your activity falls within a priority sector and which conditions apply.
- Understand how the application works. The NIPC describes a process with three phases: screening at the NIPC, certification of the production day and determination of qualifying expenditure, and certification of that expenditure by the NRS. Each phase has its own timetable, so planning should allow for them.
- Document qualifying capital expenditure as it is incurred. Invoices, contracts, payment evidence, and asset registers should be kept in a way that can be matched to the conditions of the incentive.
- Model the full tax position. Consider the incentive alongside company income tax, the development levy, and any group-level minimum tax exposure.
- Plan for change. Treat an incentive as a benefit with conditions and a defined period, not as a permanent feature of the cost base.
- Seek professional advice before committing capital. The tax treatment of an investment is easier to assess before the money is spent.
Why This Matters to Nigerian Taxpayers
A business that builds its financial plan on an incentive without checking the conditions risks a gap between expected and actual tax savings. A business that documents its qualifying spending from the start is better placed to claim what the law allows and to answer questions from the NIPC or the NRS.
Tax Implications
- Tax credits reduce tax payable and differ from deductions, which reduce taxable profit. The two should not be confused in a model.
- Capital expenditure that qualifies for the EDTI may also be relevant to capital allowances, and the interaction should be reviewed rather than assumed.
- Current NIPC guidance states that research and development carried out in Nigeria may be deductible at up to 120 percent of expenses, rising to 140 percent where it focuses on local raw materials. Conditions apply.
- Incentive claims are subject to verification, so unsupported claims can lead to adjustments and penalties.
Why Every Business Should Comply with Tax Regulation
Incentives are available to taxpayers who meet the conditions of the law, and compliance history forms part of how applications and claims are viewed. Businesses with clean records can use the advance ruling mechanism under the Nigeria Tax Administration Act to seek written clarification before a transaction, and the Tax Ombuds office if a disagreement arises.
The Advantage of Professional Guidance
Incentive rules combine tax law, investment law, and accounting. A professional consulting firm can help a business assess eligibility, organize supporting records, model the tax effect, and prepare claims. A business may also wish to confirm that its adviser holds the accreditation required under the Nigeria Tax Administration Act.
PRUDENTIAL CONSULTING LIMITED assists businesses in reviewing incentive eligibility and preparing documentation that supports their claims.
Relevant Tax Law
- Nigeria Tax Act, 2025, including the provisions on the Economic Development Tax Incentive and the Tenth Schedule of priority sectors.
- Nigeria Tax Administration Act, 2025.
- Nigerian Investment Promotion Commission guidance on the EDTI and on research and development deductions.
Frequently Asked Questions
Can countries keep competing through tax incentives indefinitely?
The practice is under pressure from minimum tax rules, revenue needs, and questions about results, and many governments are moving toward incentives that are linked to actual investment and measurable outcomes.
What replaced the Pioneer Status Incentive in Nigeria?
The Economic Development Tax Incentive, which took effect on 1 January 2026 and is described by the NIPC as a 5 percent tax credit on qualifying capital expenditure.
Does an incentive guarantee a lower tax bill?
No. Incentives depend on meeting conditions and on documentation. Group-level rules may also affect the final position for multinational groups.
Where can I get further assistance?
Contact Professional Tax Consulting Firm in Lagos, Nigeria on:
WhatsApp: 08056219998
Email: info@prudentialconsulting.com.ng
Website: https://www.prudentialconsulting.com.ng
This article is for general informational purposes and is not complete investment, tax, or legal advice. Please consult a qualified professional before making financial or tax decisions specific to your business.
Extra Media
RELATED BLOG POSTS
Global Minimum Tax: What Nigerian Multinational Businesses Need to Understand
Global Minimum Tax vs National Tax Sovereignty
New Personal Income Tax Bands Explained With Real Salary Examples
No Global Taxes: What Happens to International Tax Cooperation?
Tax Filing vs Tax Payment: Why the Difference Matters to Every Nigerian Business
Comments