
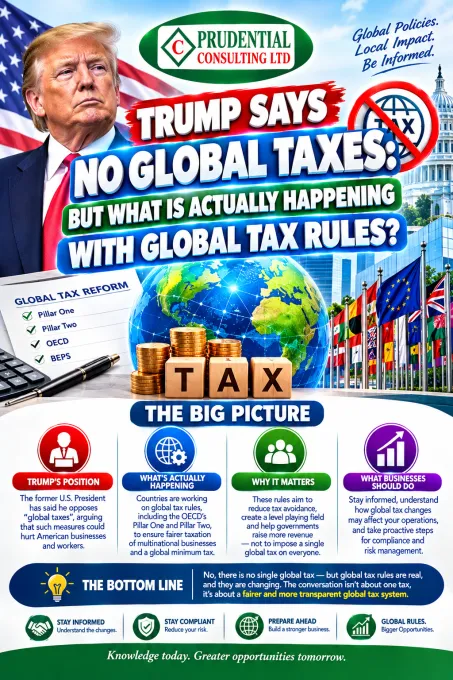
Public statements about international taxation can be short and sweeping, while the rules themselves are detailed and still evolving. For a Nigerian business, the useful question is what has changed in the text of the rules and who is affected, rather than what any headline suggests. This post sets out the position as it stands on the information available, and explains what it means for Nigerian taxpayers. What Has Happened The OECD/G20 framework. More than 140 jurisdictions worked on a two-pillar approach to taxing large multinational groups. Pillar Two sets a minimum effective tax rate of 15 percent for groups with consolidated revenue of at least €750 million.
The United States' position. In January 2025, a US presidential memorandum stated that the commitments made under the global tax deal had no force or effect in the United States without action by Congress. The Side-by-Side Package. On 5 January 2026, the OECD announced that over 145 jurisdictions in the Inclusive Framework had agreed a package that includes safe harbours and measures to coordinate implementation. In effect, it provides that groups with US parent companies are not subject to certain top-up taxes, namely the Income Inclusion Rule and the Undertaxed Profits Rule, where the US minimum tax rules are treated as equivalent. Other countries continue. Many jurisdictions have enacted their own Pillar Two legislation and continue to apply it. The package adjusts how the rules interact. It does not withdraw them. UN-level discussions. Separate discussions on international tax cooperation continue in United Nations forums, and reports indicate that changes in US participation in some international bodies could affect those processes. In short, global tax cooperation is being reshaped and made more complex, rather than ended. How This Works in Practice for a Multinational Group If a group is within scope, its effective tax rate is calculated for each jurisdiction where it operates. Where the rate falls below 15 percent, a top-up tax may arise, collected under a domestic minimum tax, under the parent-level rule, or under a backstop rule. The Side-by Side Package changes which rule applies to which groups, but the calculation and reporting burden for in-scope groups remains substantial. Step-by-Step: What a Nigerian Business Should Do 1. Check the revenue threshold. Most Nigerian businesses are far below €750 million of consolidated group revenue and are not directly in scope. 2. Identify your group position. If your company is a subsidiary of a foreign group, or has foreign subsidiaries, ask the group finance team whether the group is in scope and where it is headquartered. 3. Review how Nigerian incentives interact. Where a Nigerian entity is part of an in-scope group, the effect of a local incentive may be reduced by a top-up tax elsewhere in the group, so incentive planning should be done at group level. 4. Keep local records ready. Group-level calculations rely on accurate local financial statements and tax computations. Delays or errors at the Nigerian level can affect the group. 5. Maintain transfer pricing documentation. Nigeria's transfer pricing rules continue to apply to related-party transactions whatever happens to Pillar Two. 6. Take advice before restructuring. Group restructuring prompted by global rule changes should be reviewed for Nigerian tax consequences before it is carried out. Why This Matters to Nigerian Taxpayers Even a business outside the scope of Pillar Two can feel the indirect effects: changes in how foreign investors structure their holdings, shifts in the incentives that other countries offer, and greater attention to the documentation of cross-border transactions. For Nigeria, a stable domestic framework and accurate local compliance help investors plan with confidence. Tax Implications Nigerian tax obligations under the Nigeria Tax Act and the Nigeria Tax Administration Act apply whatever the status of international negotiations. Subsidiaries of in-scope groups should expect requests from the group for local financial and tax data in a specific format and timetable. Dividends paid to foreign shareholders remain subject to withholding tax, and the NIPC guidance states that transfer abroad is subject to evidence of tax compliance. Related-party transactions should be supported by transfer pricing documentation. Why Every Business Should Comply with Tax Regulation International rule changes make local compliance more, not less, important. Group reporting depends on reliable local numbers, and a business that files accurately and on time is a dependable part of any group structure. The Nigeria Tax Administration Act also consolidates penalties, so errors carry a clear cost. The Advantage of Professional Guidance A professional consulting firm helps a business: Determine whether it is directly or indirectly affected by global minimum tax developments. Prepare local data that supports group-level calculations. Keep transfer pricing documentation current. Follow official NRS guidance as Nigeria's own position develops.
PRUDENTIAL CONSULTING LIMITED helps Nigerian entities, including those within foreign groups, keep their local tax records and filings ready for changing international requirements. Relevant Tax Law Nigeria Tax Act, 2025. Nigeria Tax Administration Act, 2025. Nigeria Revenue Service (Establishment) Act, 2025. Nigeria's transfer pricing regulations. OECD/G20 Inclusive Framework Pillar Two rules and the January 2026 Side-by-Side Package, which are international instruments and apply in Nigeria only to the extent that they are given effect under Nigerian law. Frequently Asked Questions Has the global minimum tax been abolished? No. The Side-by-Side Package changes how the rules apply to groups with US parent companies, while many other jurisdictions continue to apply their own Pillar Two legislation. Does this affect a small Nigerian company? Generally not directly. Pillar Two applies to groups with consolidated revenue of €750 million or more. Do Nigerian tax rules change when international rules change? Not automatically. Nigerian tax obligations are set by Nigerian law, and any change in Nigeria would come through legislation or official NRS guidance. Where can I get further assistance? Contact Professional Tax Consulting Firm in Lagos, Nigeria on:
📞 WhatsApp: 08056219998
📧 Email: info@prudentialconsulting.com.ng
🌐 Website: https://www.prudentialconsulting.com.ng
This article is for general informational purposes and is not complete investment, tax, or legal advice. Please consult a qualified professional before making financial or tax decisions specific to your business.
Extra Media
Comments